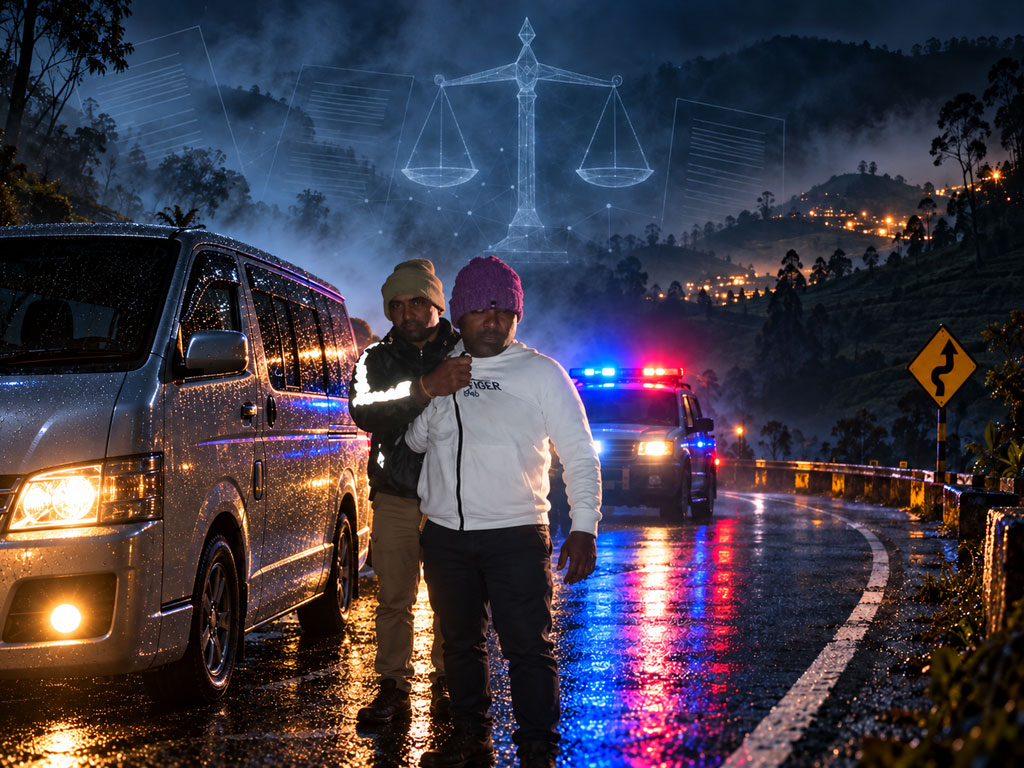
An alleged roadside seizure of a van in Nuwara Eliya has raised questions about vehicle repossession procedures and the legal responsibilities of finance companies and their agents.
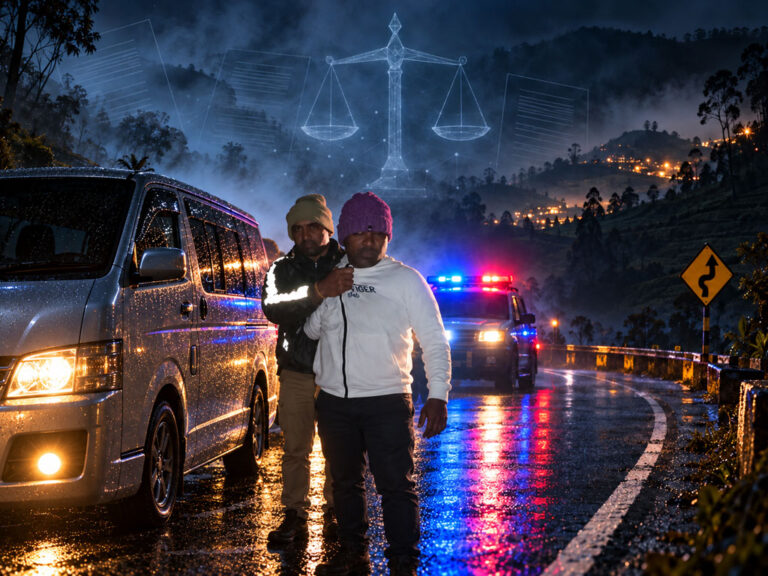
Nanu Oya Police have reportedly arrested a suspect following the alleged unauthorised repossession of a van associated with a leasing arrangement involving Mercantile Investments & Finance PLC.
According to the account provided, the vehicle was taken from a roadside location near its owner’s residence in the Blackpool area of Nuwara Eliya over reportedly outstanding lease instalments.
The vehicle owner alleges that the van was removed without his knowledge or consent and without the necessary prior legal notification.
The incident has renewed concerns about the methods used by some vehicle repossession agents and the legal procedures governing the recovery of leased vehicles in Sri Lanka.
Police Intercept Van Following Owner’s Complaint
The incident reportedly began when two individuals took possession of a van parked beside the main road near the owner’s residence.
After learning that the vehicle was being driven away, the owner pursued it.
Nanu Oya Police subsequently intercepted the van in the Phar-moston area along the Nuwara Eliya–Hatton main road, according to the report.
One suspect was arrested, while the second individual reportedly fled.
Police investigations are said to be continuing to locate the other suspect.
The vehicle owner maintains that the finance company had not provided the required prior written notice concerning the proposed repossession.
He has described the removal of the vehicle as an unlawful seizure.
Those allegations have not been independently established through court proceedings.
Police Had Previously Been Approached Over Repossession
The report further states that representatives associated with the finance company had previously approached Nanu Oya Police regarding the proposed recovery of the vehicle.
According to the account attributed to Officer-in-Charge Chief Inspector H.J.K.N. Wijerama, police advised the parties to discuss the matter with the vehicle owner and pursue a lawful, peaceful recovery process.
Despite those instructions, the vehicle was allegedly removed without the owner’s knowledge or consent.
The officer reportedly indicated that removing a vehicle by interfering with its locks or using other unauthorised means could give rise to criminal liability, depending on the circumstances.
The arrested suspect was expected to be produced before court, together with the vehicle.
The available account does not establish whether the suspect has since appeared in court, whether charges have been filed or what position the suspect has taken regarding the allegations.
What Does Sri Lankan Law Say About Vehicle Repossession?
Vehicle repossessions under finance leasing arrangements in Sri Lanka are governed by the Finance Leasing Act, No. 56 of 2000, as amended.
The law provides mechanisms through which a lessor may recover possession of leased equipment, including vehicles, following a qualifying default.
However, the right to recover a leased vehicle is subject to statutory procedures.
Section 21: Notice Requirements
Section 21 addresses notice requirements before a lessor exercises certain remedies relating to accelerated payment or termination of a finance lease.
The provision requires notice to be served by registered post and provides a period of at least seven days for the lessee to remedy the specified default.
Whether those requirements apply to a particular repossession dispute depends on the contractual circumstances and the legal remedy being pursued.
Section 27: Recovery Without Resistance
Section 27 provides a procedure for recovering possession when resistance is not offered.
It does not grant repossession agents unrestricted authority to use threats, violence or other unlawful methods to seize vehicles.
Section 28: Recovery Through Court
Where possession cannot be obtained through the procedure provided under Section 27, the Act establishes a mechanism for seeking recovery through the District Court.
The distinction is significant: a finance company may have a contractual right to recover a vehicle, but the exercise of that right must comply with the law.
Police Warn Against Forceful Vehicle Seizures
In September 2026, Sri Lanka Police publicly clarified the legal procedures applicable to vehicle repossessions.
According to the clarification, police officers are not authorised to participate directly in the repossession of vehicles by finance companies or their representatives.
Police assistance may be requested in appropriate circumstances to prevent breaches of the peace.
The Police also emphasised that where a lessee resists repossession, the lessor must pursue the applicable legal remedy rather than forcibly taking possession.
Where allegations of theft, robbery, criminal trespass or other offences arise during a repossession, police may investigate and take action if the evidence supports such offences.
These principles are relevant to the reported Nanu Oya incident, although whether any particular offence occurred must be determined through an investigation and, where applicable, court proceedings.
Questions Remain Over the Reported Incident
The central issue in the Nanu Oya case is whether those responsible for removing the van acted within the legal limits governing repossession.
Several questions remain unanswered, including whether statutory notices were issued, what authority the individuals had to take the vehicle and whether the owner had objected to the proposed recovery.
The contractual status of the vehicle and the precise circumstances of its removal will also be relevant.
The available report does not include a response from Mercantile Investments & Finance PLC.
Accordingly, it would be premature to conclude that the company itself directed or authorised any unlawful conduct.
The reported arrest highlights the importance of ensuring that disputes over unpaid vehicle instalments are resolved through lawful procedures rather than intimidation or force.
While lenders are entitled to pursue legitimate contractual remedies, borrowers are also entitled to the protections provided by law.
The outcome of the police investigation and any subsequent court proceedings will determine whether criminal liability arises from the alleged incident.
SOURCE:- HARI DESHAYA