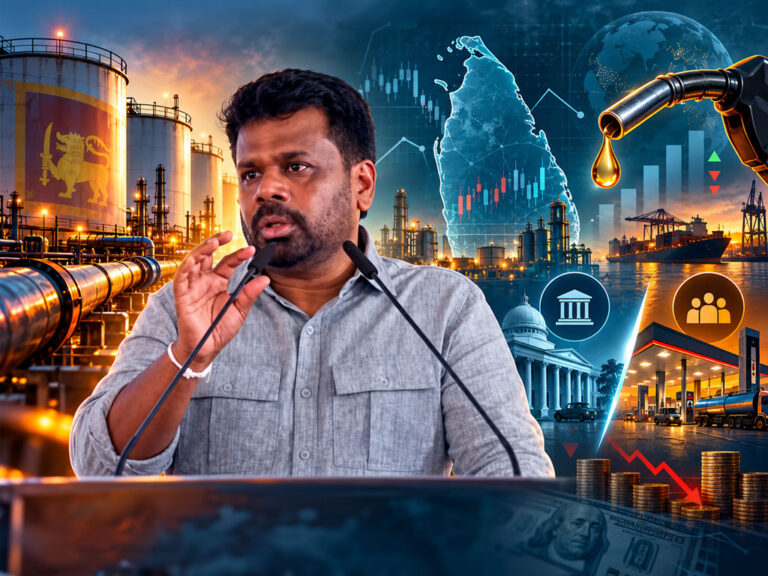
Sri Lanka’s fuel market is again under scrutiny after President Anura Kumara Dissanayake questioned the impact of private-sector competition.
COLOMBO — President Anura Kumara Dissanayake’s assertion that greater state control of Sri Lanka’s fuel market would give the Ceylon Petroleum Corporation more flexibility to manage prices has reopened a wider economic debate over competition, foreign-exchange exposure and energy security.
Speaking on October 2 during the launch of new petroleum infrastructure connected to Muthurajawela, the President argued that the CPC would have greater scope to manage price fluctuations and provide an efficient service if the market remained entirely under state control. He said the presence of private operators had reduced that flexibility.
The remarks deserve examination because Sri Lanka’s decision to admit additional international fuel suppliers was not originally based solely on the argument that private companies would outperform the CPC.
Foreign-exchange scarcity was central to the policy.
Cabinet records from June 2022 show that, during the height of the foreign-exchange crisis, the Government decided to allow companies from petroleum-producing countries to import and sell fuel using their own funding, specifically to reduce pressure on Sri Lanka’s scarce foreign currency resources.
That context complicates any suggestion that the central question is simply whether the state or private sector is better at selling fuel.
Why Private Suppliers Were Admitted
Sri Lanka’s fuel crisis in 2022 was fundamentally linked to a shortage of foreign exchange.
At that time, CPC and Lanka IOC were the principal authorised fuel importers, relying substantially on foreign currency obtained through the domestic banking system. The Ministry of Energy subsequently stated that the inability to obtain sufficient foreign exchange threatened continuous fuel supplies and wider economic activity.
The Government therefore invited additional suppliers to enter the market without using the country’s foreign-exchange reserves.
In March 2023, Cabinet approved agreements with Sinopec Fuel Oil Lanka, United Petroleum of Australia and RM Parks of the United States. Official government information stated that the selected companies were required, at least during the initial period, to source funding for fuel purchases from foreign sources.
That distinction is economically important.
A private company importing fuel with external financing does not place the same immediate demand on domestic foreign exchange as a state entity that must secure dollars locally for the same purchase.
It does not follow that every private-sector arrangement is automatically beneficial, nor that the original contracts should be immune from review. But the foreign-exchange purpose behind liberalisation cannot be excluded when assessing whether the policy succeeded.
CPC Still Holds a Dominant Position
The description of Sri Lanka’s fuel sector as having moved away from state control can also be overstated.
Official Ministry of Energy figures for 2024 show the CPC remained by far the largest distributor. Across the fuel categories recorded in the ministry’s table, CPC distributed about 3.16 million kilolitres out of a total 4.18 million kilolitres, alongside Lanka IOC, Sinopec, RM Parks and United Petroleum.
For petrol and diesel alone, the same official data show CPC retaining the largest individual share, although private companies collectively accounted for a meaningful portion of the market.
The President himself said this week that CPC’s diesel market share had risen from around 58 per cent previously to 74 per cent last month, arguing that some private suppliers had reduced sales because they were unable to compete at prevailing prices. He also said CPC recorded a Rs. 36 billion profit last year and Rs. 28 billion so far this year. Those figures were presented by the President and should therefore be treated as his stated account unless independently confirmed through audited financial statements.
If CPC can expand market share while remaining profitable, that strengthens the case that a state-owned supplier can compete successfully.
It does not, however, automatically establish that eliminating competitors would leave consumers or the economy better off.
The Foreign-Exchange Question
The strongest argument for retaining multiple suppliers is not necessarily ideological. It concerns who finances the country’s fuel imports and who carries the associated foreign-exchange risk.
Sri Lanka’s fuel import bill remains substantial.
Central Bank data show that the country spent approximately USD 4 billion on fuel imports during the first eight months of 2026 alone, a 61.6 per cent increase from the corresponding period of 2025.
Fuel imports had already cost USD 3.62 billion during January to July, reflecting the effect of higher international energy prices and geopolitical pressures.
That scale matters because petroleum competes for foreign currency with machinery, medicine, food, industrial inputs and other imports.
The original commentary supplied for this article argues that private fuel companies finance roughly USD 1 billion to USD 1.4 billion of imports annually. That specific figure could not be independently confirmed from the official material reviewed and should not be treated as an established current statistic without supporting company or government data. Pasted text
The broader principle, however, is documented: the additional companies were admitted specifically on the basis that they would procure fuel without placing the same pressure on Sri Lanka’s foreign-exchange reserves.
Reserves Are Stronger, but They Are Not Unlimited
Sri Lanka’s reserve position is considerably stronger than during the 2022 crisis.
The Central Bank reported gross official reserves of USD 6.9 billion at the end of August 2026, including the swap facility with the People’s Bank of China.
That figure is materially different from the USD 5.5 billion “spendable reserve” cited in the supplied commentary. Gross reserves and immediately usable reserves are not necessarily the same concept, but any argument based on a USD 5.5 billion figure should identify precisely how that number was calculated before using it to estimate the impact of fuel imports. Pasted text
The economic question therefore cannot be reduced to whether the Government technically possesses enough foreign exchange to import all fuel itself.
Policymakers must also consider the opportunity cost of committing more state-controlled foreign currency to petroleum when private suppliers are prepared to finance part of the import requirement externally.
Competition Versus Monopoly
There is also a broader competition question.
A state monopoly can potentially simplify procurement, distribution and price administration. If the operator is efficient and financially strong, economies of scale may also reduce certain costs.
Competition can produce different benefits. Multiple suppliers diversify procurement risk, create pressure to improve efficiency and reduce dependence on a single institution.
Neither structure automatically guarantees lower retail prices.
Fuel pricing depends on global crude and refined-product prices, exchange rates, taxation, freight costs, financing, inventories and the pricing formula applied domestically.
The relevant test is therefore not whether state ownership or private ownership is inherently superior.
It is whether the market structure delivers reliable fuel supplies, competitive costs, transparent pricing and the lowest reasonable exposure for taxpayers and the country’s external reserves.
A Debate That Needs More Than Political Rhetoric
President Dissanayake is entitled to question whether the liberalisation programme introduced by the previous administration achieved its intended objectives.
His argument that CPC has increased market share while remaining profitable provides one basis for evaluating that policy.
But the assessment must also account for why private suppliers were brought in: Sri Lanka had experienced severe fuel shortages because the country could not obtain enough foreign exchange to finance imports.
Removing private participation would consequently involve more than changing who operates filling stations. It could change who must find the dollars required to finance a substantial portion of the national fuel bill.
Sri Lanka’s experience since 2022 therefore points to a more useful policy question than whether the state or private sector should “win” the fuel market.
The question is what combination of state capacity, private capital, competition and regulation gives the country the most secure fuel supply at the lowest sustainable economic cost.