By Roy Denish.
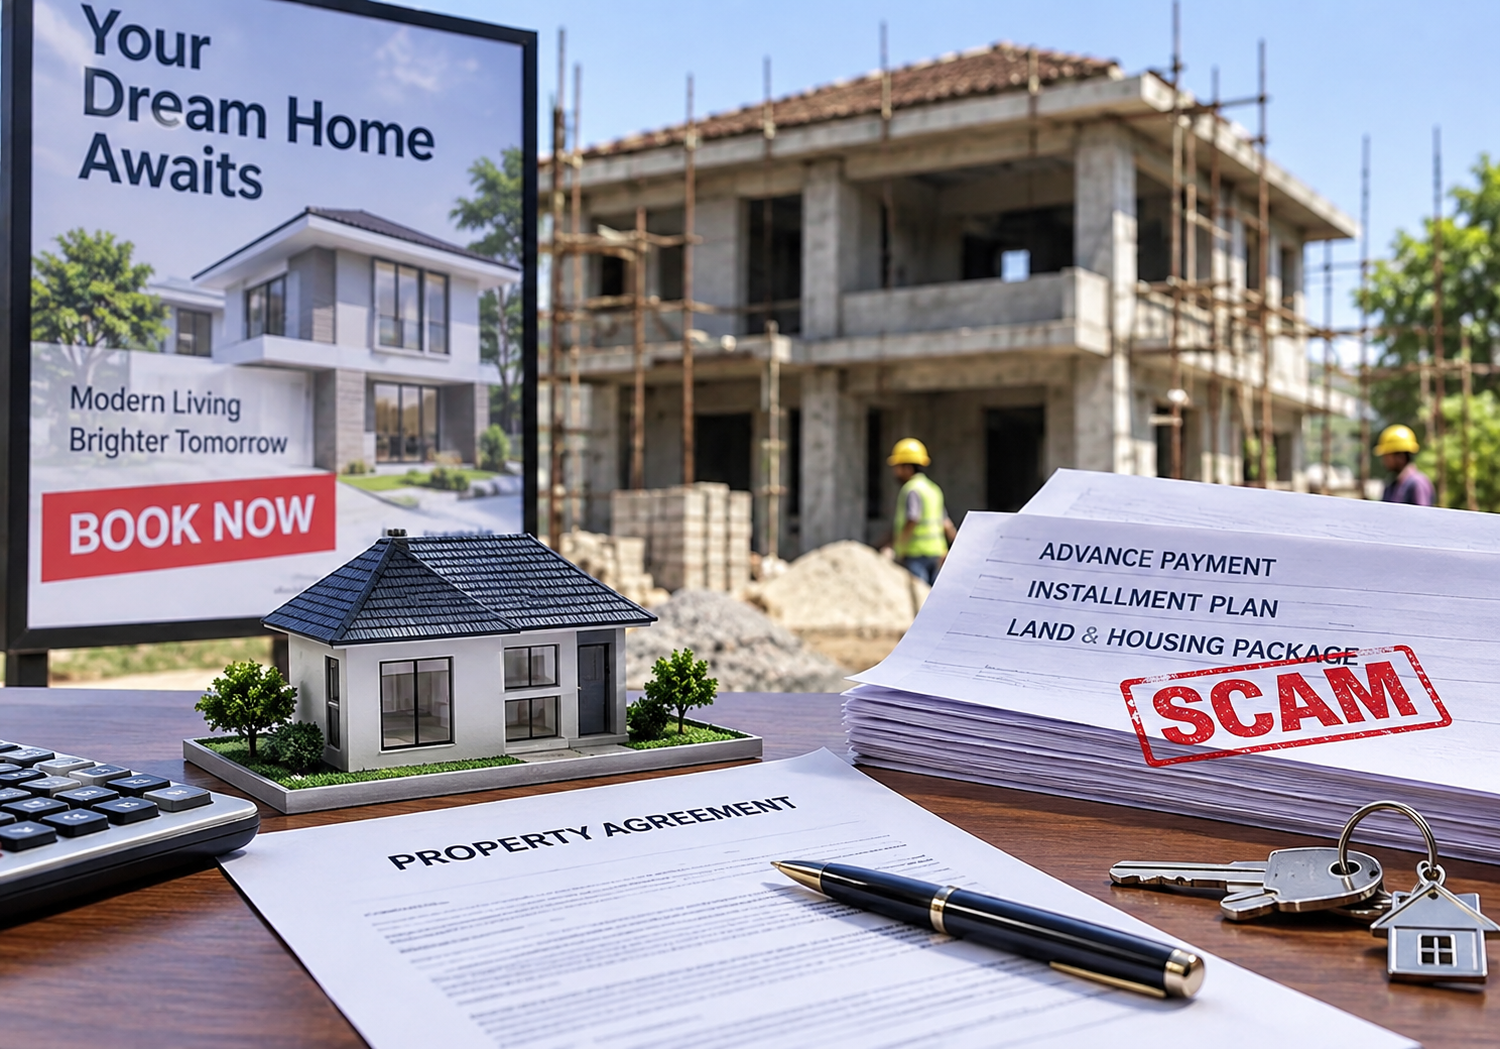
An alleged Sri Lanka housing scam involving 245 complainants has led to arrests after customers said homes and refunds never materialised
For many people, owning a home represents a lifelong dream — a symbol of security, stability, and years of hard work.
But when fraudulent schemes exploit that aspiration, the consequences extend far beyond financial losses.
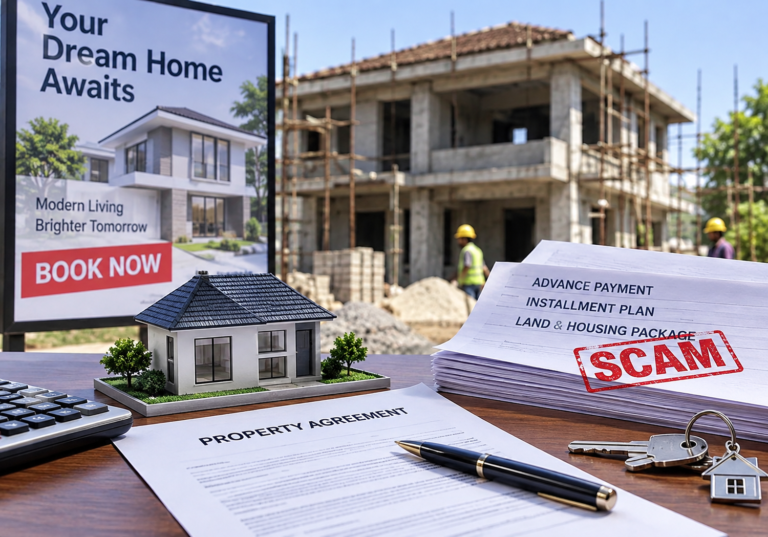
An alleged housing and land fraud has recently come to light in Sri Lanka, with a private company accused of defrauding 245 individuals of substantial sums of money through what was promoted as an affordable housing scheme.
Operating primarily through social media advertisements, the company allegedly promised prospective homeowners a straightforward path to building houses and acquiring land through manageable instalment plans.
Attracted by the promise of affordability amid rising economic pressures, customers reportedly entered into agreements with the company and paid substantial advance amounts, in some cases amounting to approximately 60% of the total value of the promised property.
However, according to complaints, months passed without construction materials being delivered to the sites, while the promised houses failed to materialise.
When customers demanded refunds, the company allegedly issued cheques that were later dishonoured, leaving complainants without either their homes or their money.
Following a growing number of complaints, the Mirihana Special Crimes Investigation Unit launched an investigation into the company’s operations.
Law enforcement action has since escalated, with the director of the private company, its chief sales manager, and an operations officer reportedly arrested and remanded.
The scale of the case, involving as many as 245 formal complaints, has also raised questions about weaknesses in consumer protection and regulatory oversight.
In difficult economic conditions, consumers can become particularly vulnerable to companies offering seemingly affordable alternatives.
The case has renewed discussion about possible preventive safeguards, including escrow arrangements for large advance payments, stronger background checks on company directors, and closer regulatory monitoring of housing and property-development businesses.
Until stronger safeguards are in place, consumers are advised to independently verify developers, seek legal advice before signing major contracts, and exercise caution when companies demand unusually large advance payments before construction begins.
As investigations continue, a broader question remains: what regulatory reforms are required to prevent consumers from losing their life savings before authorities are able to intervene?